English
 Español
 Français
 Deutsch
 Italiano
 Português
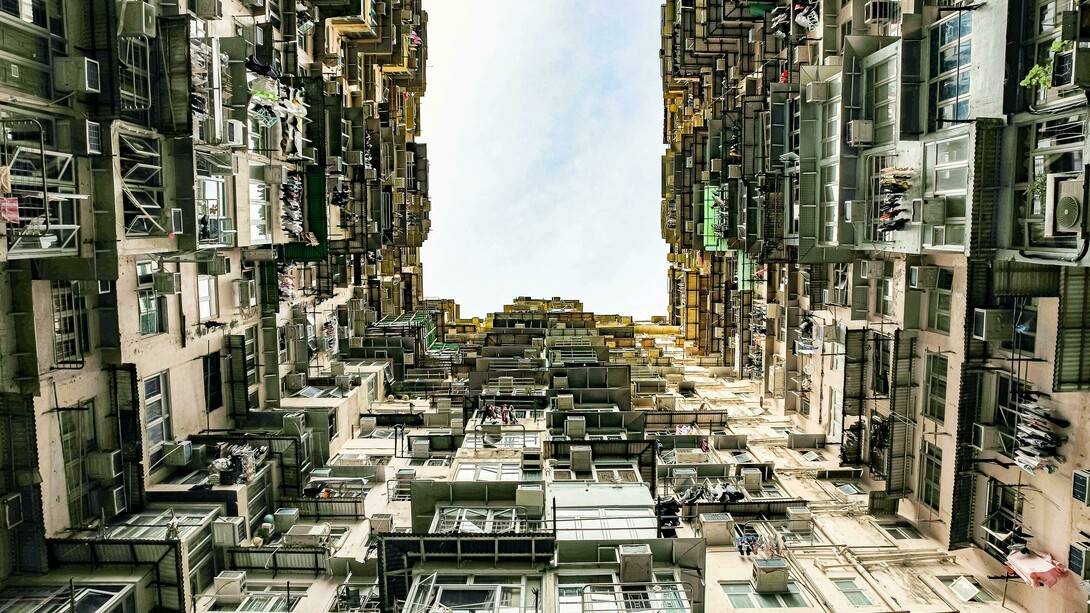
You’ve probably heard the explanation a thousand times: housing is expensive because there isn’t enough of it. If we just build more homes, prices will eventually fall. It sounds logical, almost obvious. But if that were the full story, the housing crisis wouldn’t have lasted this long, and it definitely wouldn’t have spread across so many countries at once. In reality, even in places where construction has increased, affordability has barely improved. Something deeper is going on beneath the surface.
Over the last few decades, housing has quietly changed its role in the global economy. It’s no longer just a place to live—it’s also one of the most important financial assets in the world. Homes are now widely treated as investment vehicles, not just by individual buyers but by large institutional players like real estate funds, private equity firms, and international investors. This shift means that housing prices are no longer driven only by local people needing somewhere to live butalso by global capital looking for stable returns.
That changes everything about how the market behaves. When housing becomes a financial asset, it starts to follow financial logic. Investors aren’t just thinking about shelter or community needs; they’re thinking about yield, appreciation, and long-term value growth. In many cities, this means that a significant share of new housing is either bought as an investment or designed in a way that maximisesmaximises profit rather than affordability. Even when more homes are built, they don’t necessarily filter down to the people who need them most.
There’s also a timing issue that makes the situation worse. After the 2008 financial crisis, and again during the pandemic, interest rates stayed unusually low for a long period. Borrowing money became cheap, and that made property extremely attractive. Not just for people buying homes, but also also for investors who could borrow at low cost and park money in real estate. Housing prices rose steadily in many countries during this period, and even when rates increased later to control inflation, prices didn’t simply reverse. The system had already shifted.
What makes housing different from most other markets is that it’s both local and global at the same time. You can’t import more housing from somewhere else if prices go up in your city. At the same time, global money can flow into your local market. That imbalance creates pressure that builds over time. Cities with strong job markets or cultural appeal become magnets for investment, which pushes prices higher even if more homes are being constructed. Supply increases, but demand increases faster and in a very different form.
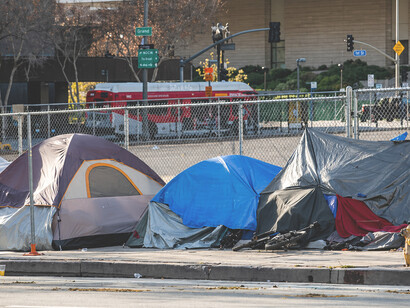
This is one of the key reasons younger generations feel locked out. For many Gen Z and younger millennials, the idea of buying a home feels less like a delayed milestone and more like a completely different game. Wages in most countries have not kept pace with housing prices, and the gap between income and property costs has widened significantly. On top of that, saving for a deposit has become much harder, especially in cities where even renting takes up a large portion of monthly income. In many cases, access to housing now depends heavily on family wealth, not just personal earnings.
This isn’t just a big-city problem either. While cities like London or Amsterdam are often used as examples, similar patterns are showing up in smaller urban areas as well. As remote work expands and global investment spreads, pressure is no longer concentrated in just a few famous cities. Housing markets in mid-sized cities are increasingly influenced by the same financial forces, which means affordability issues are becoming more widespread rather than isolated.
Governments often respond by trying to increase supply through construction incentives or zoning reforms, and these policies do matter. But they don’t fully address the fact that demand itself has changed. When housing is treated as an investment, new supply doesn’t automatically translate into lower prices or more accessible homes. It can simply become another asset class for capital to absorb.
The result is a housing system that feels increasingly disconnected from its original purpose. Even when more homes are built, affordability doesn’t improve in a straightforward way because the forces shaping prices go beyond local supply and demand. They now include global investment flows, financial strategy, and long-term wealth storage.
The reality is that housing today serves two roles at once: it is both shelter and a financiala financial asset. And when those two roles compete, the financial side often dominates. That is why the crisis feels so persistent, even when policy attempts are made to fix it.
The uncomfortable conclusion is that this is no longer just a problem of building more homes. It is a structural shift in how housing fits into the global economy. And until that shift is addressed, affordability will remain one of the defining economic issues of this generation.