English
 Español
 Français
 Deutsch
 Italiano
 Português
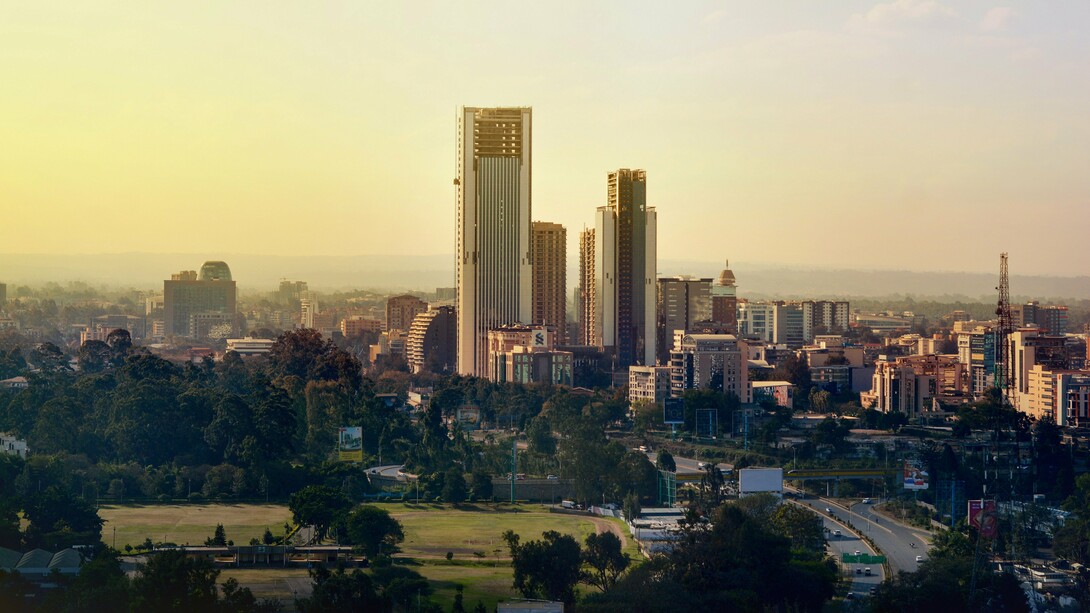
The ascendancy of Kenyan mobile money as a global leader was not initiated in a state of the art laboratory or a rich financial center. It started in the life of ordinary people, being conditioned by the efforts of people who attempted to find an answer to an easy yet pressing question: how to transfer money without any danger over distance. During a period when the nation was mostly locked out of established banking frameworks, few would have imagined that it would end up being the home of one of the most impactful financial developments in the modern history.
At the beginning of the 2000s, banking access in Kenya was even and unequal. The majority of the population and especially those in the rural regions, lacked access to bank accounts and an easy means of sending or receiving money. When a person in the city had to feed the family at home, the procedure was unpleasant and unpredictable. Money would be frequently transported by bus drivers or informal messengers putting it at risk of theft, or wastage. The financial system was just not indicative of the Kenyan life.
However, as the banks were trying to cover the population, mobile phones were infiltrating silently. The handsets were basic and were found throughout the nation, crossing across income and geography. This prevalence of mobile technology provided a surprising basis of change. What Kenya would lose in banking infrastructure, it would earn back in connection, and that would turn out to be the determining factor.
In 2007, Safaricom, the leading telecommunications company and digital innovator, launched a service that would change the face of finance: M-Pesa. Originally intended as an easy-to-use system to repay microfinance loans, M-Pesa enabled users to deposit money with registered agents, transfer it through SMS, and redeem it at other locations. It was a simple concept, based on already available technology, yet it soon assumed a life of its own.
Kenya adopted the usage of M-Pesa in a manner that no one could have ever anticipated. It was used as a means of remitting money home, paying bills, purchasing goods and covering day to day expenses. What began as a niche service quickly turned into a national payment system. Its ease, speed, and dependability enabled it to reach out to millions of people, including those who had never dealt with a bank previously. The real need for an alternative in the country was one of the major causes of this success.
Mobile money was forced to contend with the traditional banking systems in most of the world. In Kenya, it took the place of a gap left open by banks. It was not a substitute for an already functioning thing; it provided an answer to a problem that was not there in the first place. This not only made adoption likely but also inevitable.
The regulator approach was another significant element. Rather than opting for closure or a massive ban on the new service, Kenyan authorities permitted it to expand but kept a check on it. This equilibrium promoted creativity and instilled confidence in the people. Meanwhile, M-Pesa depended on a huge number of local agents, small shop owners and kiosks, who helped people to turn cash into digital money and vice versa easily. This decentralised structure brought financial services nearer to the population like none other bank.
With time, M-Pesa has grown to include more than just transfers. It expanded to become a complete financial ecosystem, providing saving facilities, loans, bill payment, and even investments. It was more than a service to many of the users; it was their main financial tool. Millions of people in a country whereby traditional banking was previously a far-fetched dream now had access to an effective and dependable financial system in their pockets.
The effects on the daily lives in Kenya have been tremendous. Families are now able to help one another in real-time and no matter the distance. It allows small businesses to receive payments without having to handle cash, which enhances efficiency and decreases risk. In case of an emergency, money may be moved in a matter of seconds and this comes with some financial strength, which was never dreamed of. In most aspects, mobile money has turned into an unseen infrastructure of life.
Outside its borders the innovation of Kenya started to attract the attention of the world. The M-Pesa model was studied by countries in Africa, Asia, and other countries and hoped to achieve the same success. Although not all initiatives had the same magnitude, the main concept was spreading fast: mobile phones could be used to provide financial services, without having to go to the traditional banking framework. Kenya had shown a new direction.
This change compelled the banking industry across the world to change its mindset. Previously characterized by physical locations and paperwork, banks started investing in the digital platform. Financial systems in every corner of the world became mobile, instant transfers and digital wallets became the norm. There was also a renewed urgency about the concept of financial inclusion, as states and institutions tried to access populations previously marginalised.
The influence of Kenya was even more profound. It broke the traditional view of innovation as being a flow between developed and developing countries. This was the reverse in this situation. An invention out of necessity in a developing country was a prototype to the other world. It demonstrated that great innovation is usually based on an insight into actual issues and creating solutions that are relevant to the lives of people. Mobile money is evolving today. In Kenya, the range of new services keeps growing, including the state-of-the-art credit services or investment platforms. It is not simply a matter of sending money anymore, but it is a matter of facilitating economic participation on a larger scale. It is a symbol of opportunity, access and financial independence to many users.
The story of Kenya is astonishing not only because of the technology but also because of the people who made it. Mobile money was successful because of ordinary people who adopted it, modified it, and personalised it. It was not foisted on a people; it developed naturally, and was moulded by the necessities and customs of those who depended on it.
Kenya is not a country that took a conventional route to becoming the world leader in mobile money. It has done it by acting creatively and practically to a challenge. It has revolutionised not only its own economy, as it has turned a mere mobile phone into a financial tool but also the mindset of the world when it comes to money.